Florida Cash-Out Refinance
Cash-Out Refinance Florida
Turn Your Home Equity Into Cash
A cash-out refinance replaces your existing mortgage with a new, larger loan and gives you the
difference in cash at closing. Mortgages Done Right shops multiple lenders to help Florida homeowners
compare cash-out refinance options based on their equity, goals and qualifications.
500+ 5-Star Reviews Across Platforms 30+ Years Experience Access to 25+ Lenders Florida Mortgage Broker
The Basics
What Is a Cash-Out Refinance?
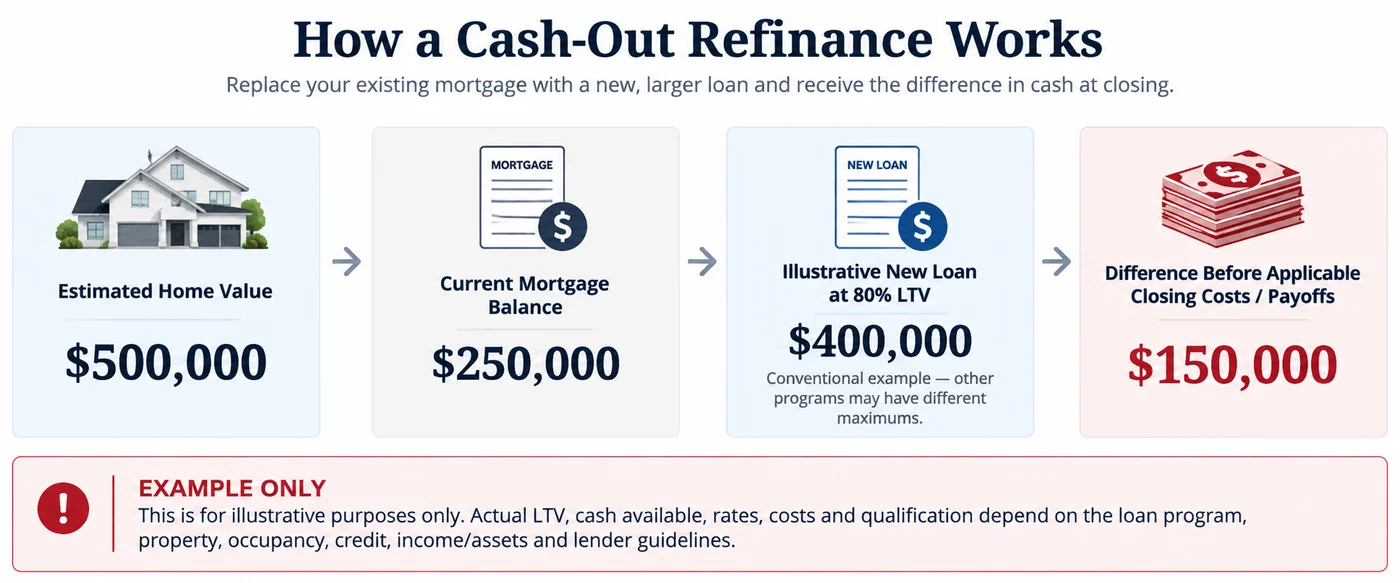
A cash-out refinance replaces your current mortgage with a new mortgage for a larger amount. Your
existing mortgage is paid off and, after applicable closing costs and payoffs, you receive the eligible
remaining proceeds in cash.
- Estimated home value
- $500,000
- Current mortgage balance
- $250,000
- Illustrative new loan at 80% LTV
- $400,000
- Difference before closing costs/payoffs
- $150,000
This is an illustration only. Actual maximum loan-to-value, cash available, rates, costs and
qualification depend on the loan program, property, occupancy, credit, income/assets and lender
guidelines. Not every borrower or property will qualify for 80% loan-to-value.
Putting Equity to Work
Ways Florida Homeowners Use Their Equity
Cash-out proceeds can generally be used for a variety of purposes, subject to applicable loan and
program requirements.
Debt Consolidation
Combine higher-interest balances into a single mortgage payment.
Home Improvements & Renovations
Fund updates, repairs or additions to your property.
Major Purchases or Expenses
Address significant planned or unplanned costs.
Investment Opportunities
Use eligible proceeds toward other financial or investment goals.
Education Expenses
Help fund tuition or other education-related costs.
Emergency or Financial Reserves
Build accessible reserves for future needs.
This information is general in nature and is not tax advice. Please consult a qualified tax professional
about your specific situation.
Broker vs. Bank
Why Work With Mortgages Done Right?
Instead of offering only one institution’s mortgage products, Mortgages Done Right can compare cash-out
refinance programs from 25+ lenders.
Compare multiple lending options rather than relying on one bank.
Experienced mortgage guidance for straightforward and complex borrower situations.
Serving homeowners throughout Florida from our Boynton Beach office.
Speak with an experienced mortgage professional about your goals, equity and available options.
Compare Your Options
Cash-Out Refinance vs. HELOC: What’s the Difference?
| Cash-Out Refinance | HELOC | |
|---|---|---|
| Existing Mortgage | Replaces the existing first mortgage | Generally leaves the existing first mortgage in place |
| Structure | Provides eligible proceeds at closing | Creates a separate line of credit / second lien |
| Payments | One new first-mortgage payment | Separate payment |
| Rate | Rate and term on the entire first mortgage change | Often has a variable interest rate |
| Costs | Standard refinance closing costs may apply | Costs and terms vary by lender |
The right option depends on your existing mortgage rate, how much equity you need, how long you expect to
borrow the money and the costs and terms available to you. Mortgages Done Right can help compare the
alternatives, including other refinancing solutions.
For a closer look at each option, see our
HELOC vs. Cash-Out Refinance Florida guide
and our
Home Equity Loan vs. HELOC comparison.
Your Equity
How Much Equity Can You Access?
The amount you may be able to access depends on several factors specific to you and your property,
including:
- Current property value
- Existing mortgage balance
- Loan program
- Property type
- Primary residence vs. second home/investment property
- Credit profile
- Income/assets and underwriting
- Maximum allowable loan-to-value (LTV)
Some conventional primary-residence cash-out scenarios may allow financing up to 80% of the property’s
value, subject to program and borrower requirements. This is not available or guaranteed for every
borrower, property or loan program. Other programs can allow a higher combined loan-to-value — for
example, eligible VA cash-out refinances can permit financing up to 100% of the property’s value under
applicable VA guidelines, and some other home-equity programs may have higher CLTV limits depending on
lender and program guidelines.
Explore Related Guides
Detailed reading on cash-out refinance mechanics, pricing and planning:
Options Through Our Lender Network
Cash-Out Refinance Options for Different Borrowers
Every homeowner’s situation is different. As a mortgage broker working with 25+ lenders, Mortgages Done
Right can help compare cash-out refinance options across several program types depending on your
property, income documentation and goals. Not every lender offers every program below.
Conventional Cash-Out Refinance
Traditional cash-out refinance options for qualified homeowners. Maximum LTV and qualification depend
on occupancy, property type and applicable program guidelines.
FHA Cash-Out Refinance
FHA cash-out refinancing may be available to eligible owner-occupant homeowners with sufficient equity
who meet applicable FHA requirements.
VA Cash-Out Refinance
Eligible Veterans and service members may have VA cash-out refinance options with different allowable
LTV guidelines than conventional financing, subject to VA eligibility, entitlement, appraisal,
underwriting and lender requirements.
Jumbo Cash-Out Refinance
Homeowners with higher-value properties or larger loan amounts may have jumbo cash-out options.
Maximum loan amounts, LTV and reserve requirements vary significantly by lender and program.
DSCR Investor Cash-Out Refinance
Real estate investors may be able to cash out equity from rental properties using a DSCR loan, where
qualification can be based primarily on the property’s rental income and debt-service coverage rather
than traditional personal-income documentation. Requirements vary by lender.
Bank Statement Cash-Out Refinance
Self-employed borrowers may have cash-out refinance options using eligible bank-statement deposits to
document income rather than relying solely on traditional tax-return income calculations. Program
requirements vary by lender.
Foreign National Cash-Out Options
Foreign national property owners may also have cash-out refinance options on eligible U.S./Florida real
estate through certain specialty lenders, subject to lender guidelines, property type, equity,
documentation, reserves and other requirements. Learn more about
Foreign National Loans.
One Property. More Than One Way to Access Equity.
Mortgages Done Right works with 25+ lenders, giving Florida homeowners, self-employed borrowers, real
estate investors and foreign national property owners access to a broader range of cash-out refinance
programs than a single loan program or lender may offer.
A Clear Starting Point
How a Cash-Out Refinance Works
Tell Us About Your Property
We review your estimated property value, current mortgage balance and cash-out goal.
Compare Loan Options
We compare available programs from our lender network based on your situation.
Complete the Mortgage Process
Documentation, underwriting, title and appraisal requirements are completed as applicable.
Close & Receive Eligible Proceeds
Your existing mortgage and applicable obligations are paid through closing and eligible remaining
cash-out proceeds are disbursed according to closing requirements.
Is This Right for You?
Is a Cash-Out Refinance Right for You?
It may be worth exploring for homeowners who:
- Have built meaningful home equity
- Need access to a larger amount of cash
- Want to consolidate higher-interest obligations
- Are planning substantial home improvements
- Want to use equity for another financial objective
- Understand that their existing mortgage will be replaced
An Important Note
A cash-out refinance is not automatically the best choice for every homeowner. Your current mortgage
rate, new rate, closing costs, monthly payment, loan term and alternatives such as a HELOC or home
equity loan should all be considered.
Serving Homeowners Statewide
Cash-Out Refinancing Throughout Florida
Mortgages Done Right works with homeowners throughout Florida and can help compare available cash-out
refinance programs, including homeowners in
Palm Beach County,
Broward County,
Miami-Dade County,
Martin County
and homeowners throughout Florida.
Our physical office remains 1500 Gateway Blvd Suite 220, Boynton Beach, FL 33426. We work with borrowers
by phone, online and by appointment; we do not maintain additional physical office locations.
Frequently Asked Questions
Florida Cash-Out Refinance FAQs
What is a cash-out refinance?
A cash-out refinance replaces your current mortgage with a new mortgage for a larger amount. The
existing mortgage is paid off, and after applicable closing costs and payoffs, you receive the
eligible remaining proceeds in cash.
How much cash can I take out of my Florida home?
The amount depends on your property value, current mortgage balance, loan program, occupancy, property
type, credit profile, income/assets and the maximum allowable loan-to-value for your scenario. Some
conventional primary-residence programs may allow up to 80% LTV, but this is not universal and depends
on lender guidelines and your qualifications.
Can I use a cash-out refinance to pay off credit cards or other debt?
Many homeowners use cash-out proceeds for debt consolidation, subject to applicable loan and program
requirements. Greg can help you compare whether this makes sense based on your current rates, balances
and overall financial picture.
Can I use cash-out funds for home improvements?
Yes, home improvements and renovations are a common use of cash-out refinance proceeds, subject to
applicable loan and program requirements.
What credit score do I need for a cash-out refinance?
Credit requirements vary by loan program, lender and overall borrower profile, including income,
assets, property type and loan-to-value. Greg can review your specific situation and help identify
programs that may fit.
Does a cash-out refinance change my mortgage rate?
Yes. Because a cash-out refinance replaces your existing mortgage with a new one, the rate and terms on
the new, larger loan apply to the entire balance going forward.
What is the difference between a cash-out refinance and a HELOC?
A cash-out refinance replaces your existing first mortgage and provides eligible proceeds at closing,
resulting in one new first-mortgage payment. A HELOC generally leaves your existing first mortgage in
place and adds a separate line of credit, often with a variable rate and its own payment. The right
option depends on your rate, equity needs, borrowing timeline and available costs and terms.
Can I do a cash-out refinance on an investment property?
Cash-out refinance options may be available for eligible investment properties, though requirements,
available loan-to-value and documentation can differ from primary-residence programs. Greg can review
your property and goals to identify potential options.
Are there closing costs with a cash-out refinance?
Standard refinance closing costs may apply, and the specific costs depend on the lender, loan program
and loan amount. These costs, along with your new rate and term, should be part of any comparison
before deciding to move forward.
How long after buying or refinancing a home can I do a cash-out refinance?
There is no single universal waiting period that applies to every loan. Requirements vary by loan
program and lender, and conventional agency programs may impose ownership or current-loan seasoning
requirements. Greg can review your specific timeline and loan history to explain what may apply to
your situation.
Next Step
See What Your Florida Home Equity Can Do for You
If you’re considering a cash-out refinance, start by finding out what options may be available based on
your property, mortgage balance and goals. Mortgages Done Right can compare programs from multiple lenders
and explain the numbers before you decide.
Mortgages Done Right Inc.
1500 Gateway Blvd Suite 220, Boynton Beach, FL 33426
Mortgages Done Right Inc. is a mortgage broker, not a direct lender, and works with 25+ wholesale lenders to help compare available loan programs. Loan programs, interest rates, pricing, credit requirements, equity requirements, appraisal requirements, documentation requirements and availability are subject to change and lender approval. This page is for general informational purposes only and is not a commitment to lend, and is not tax or financial advice. Mortgages Done Right Inc. NMLS #1532755. Greg Hayden NMLS #332209.
Important Loan Information
Mortgages Done Right Inc. is a Florida mortgage broker located at 1500 Gateway Blvd, Suite 220, Boynton Beach, FL 33426. NMLS #1532755. Loan programs, rates, terms, eligibility requirements and closing costs vary by lender, loan program and borrower qualifications. Mortgages Done Right Inc. does not charge borrowers a fee unless disclosed as part of the applicable loan transaction. Third-party lender, appraisal, title, credit, government and other closing costs may apply. Equal Housing Opportunity.