Westlake Mortgage Broker for New Construction, Builder Incentives and Complex Borrowers
Mortgages Done Right helps Westlake buyers compare builder-preferred financing with conventional, FHA, VA, jumbo, bank-statement, asset-based and other wholesale mortgage options.
Builder incentives can be valuable and may sometimes provide the strongest available financing package. The important step is comparing the entire offer—including the interest rate, APR, discount points, lender fees, closing-cost credit, mortgage insurance, cash required and long-term payment.
Work directly with Greg Hayden, a Palm Beach County mortgage broker with more than 30 years of experience and access to over 25 wholesale lenders. When the builder’s financing is clearly better, Greg will tell you. When another lender provides better qualification, flexibility or long-term value, you will understand those alternatives before committing.
Years of Experience
Loans Closed
Wholesale Lenders
Five-Star Reviews
What Makes Financing a New Westlake Home Different?
Purchasing new construction involves more than selecting a floor plan. Incentives, deposits, completion dates, rate locks, appraisals and lender requirements should be reviewed together.
New Construction
Financing must coordinate with the construction schedule, final appraisal, certificate of occupancy and the builder’s closing requirements.
Builder Incentives
Incentives may include closing-cost credits, rate buydowns, reduced pricing, design upgrades or benefits tied to the builder’s preferred lender.
Extended Rate Locks
Longer construction periods may require extended locks, float-down options or an understanding of extension costs if completion is delayed.
First-Time Buyers
Conventional, FHA, VA and eligible assistance options may help qualified buyers manage down payment and closing expenses.
Move-Up and Relocation Buyers
Buyers may need to coordinate the sale of another property, deposits, down-payment funds, temporary housing and closing dates.
Self-Employed Borrowers
Bank-statement, profit-and-loss, asset-based and other Non-QM options may help eligible borrowers who do not fit builder-lender guidelines.
Should You Use the Builder’s Preferred Mortgage Lender?
Sometimes the answer is yes. A builder may subsidize a rate, contribute toward closing costs or offer another financial benefit that an outside lender cannot duplicate.
However, the builder lender may not offer every program or provide the best qualification method for self-employed buyers, retirees, investors, buyers with complex income or borrowers needing a specialty mortgage.
Greg compares the builder’s complete offer with available wholesale alternatives. The goal is not to claim that another lender always wins. The goal is to help you understand which financing package is truly strongest for your circumstances.
Builder Financing May Be Strongest—But It Is Not the Only Option
Each financing approach has advantages. The right decision depends on the incentive, borrower qualification, mortgage program and long-term cost.
Builder-Lender Advantages
Subsidized rates, closing-cost credits, coordinated construction updates and incentives unavailable through an outside lender.
Wholesale-Lender Advantages
Access to multiple lenders, broader qualification methods and programs not offered by every affiliated builder lender.
When the Builder Wins
When the subsidy creates the lowest complete cost and the borrower fits the preferred lender’s guidelines, it may be the best choice.
When Another Lender Fits Better
Complex income, bank statements, asset depletion, credit considerations or specialty programs may require a different lender.
Do Not Compare Mortgage Offers Using the Interest Rate Alone
A lower advertised rate may require discount points, a higher purchase price or the loss of another incentive. Review each component before deciding.
Note Rate
The contractual interest rate used to calculate the principal-and-interest payment.
APR
A broader cost measurement that may include eligible points, lender charges and financing costs.
Closing-Cost Credit
Money contributed toward eligible settlement expenses, subject to loan-program limitations.
Discount Points
Upfront funds paid to obtain a lower interest rate, which should be evaluated against the expected ownership period.
Mortgage Insurance
Monthly or upfront insurance costs can materially affect the complete payment and financing comparison.
Cash to Close
The total amount needed for down payment, closing costs, prepaid expenses, deposits and applicable credits.
Lender Fees
Origination, underwriting, processing and other lender charges can differ between offers and should be compared line by line.
Builder Incentives
Closing-cost credits, buydowns, price reductions or upgrades may depend on using a specific lender, so confirm exactly what is required to receive them.
Payment and Time Horizon
Compare the estimated total monthly payment, including mortgage insurance where applicable, and how long you expect to keep the loan before choosing between a lower rate and lower upfront cost.
Compare the Builder’s Mortgage Offer Before You Decide
Builder incentives can be valuable. The question is whether the total package is better after comparing the rate, fees, credits and payment.
Have a builder loan estimate or incentive sheet? Contact Greg for a side-by-side comparison.
Mortgage Options the Builder’s Lender May Not Offer
Program availability depends on the borrower, property, occupancy, credit, income documentation, available assets and lender requirements.
Conventional Loans
Purchase financing for qualified primary residences, second homes and eligible investment properties.
FHA Loans
Government-backed financing for eligible primary-residence buyers, including qualified first-time purchasers.
VA Loans
Purchase options for eligible veterans, active-duty service members and qualifying surviving spouses.
Jumbo Loans
Financing for qualified borrowers purchasing larger Westlake homes requiring higher loan amounts.
Bank Statement Loans
Alternative income documentation for eligible self-employed borrowers whose tax returns may understate financial strength.
View All Loan Programs
Explore asset-based, investor, reverse mortgage, foreign-national and additional specialty options.
Declined by the Builder’s Lender? Ask About Other Options
A decline from one lender does not necessarily mean you cannot qualify elsewhere. Lenders use different guidelines, and a builder’s preferred lender may not offer every income-documentation method or loan program. Greg reviews your situation against more than 25 wholesale lenders to see whether another path may fit.
Self-Employed and Business Owners
Bank-statement and profit-and-loss options may be available when tax returns do not reflect your full income.
Complex or Variable Income
Commission, bonus, multiple income sources or recent job changes may be reviewed differently by different lenders.
Asset-Based Qualification
Asset-based and asset-depletion options may help eligible borrowers who have substantial assets but less traditional income.
Different Lender Guidelines
Conventional, FHA, VA, jumbo and Non-QM guidelines vary by lender, so another lender may review the same file differently.
Approval is never guaranteed, and every loan is subject to credit, income, asset, property and underwriting review.
Westlake Mortgage Calculator
Estimate a monthly mortgage payment for a Westlake new-construction home, move-up purchase, primary residence or refinance.
Your actual housing payment may also include Florida property taxes, homeowners insurance, mortgage insurance, HOA costs and other property-related expenses. Greg Hayden can help you compare the complete payment with builder incentives and available wholesale mortgage options.
A Calculator Estimates. Greg Compares.
Estimate the payment online, then speak with Greg about builder credits, rate buydowns, closing costs, loan programs and outside lender alternatives.
Ask About the Westlake HAPPY Program
The City of Westlake’s Housing Assistance Purchase Program Yearly—known as HAPPY—is designed to support eligible attainable and workforce homeownership within the city.
Depending on current program guidelines and available funding, qualified buyers of eligible new construction in Westlake may receive assistance toward eligible transaction costs such as down payment, closing costs and certain interest-rate buydowns.
The program has its own eligibility, underwriting, funding and timing requirements, all controlled by the City of Westlake. Funding is not guaranteed, and mortgage approval remains subject to lender requirements. A mortgage preapproval is generally part of the process, and buyers should confirm current guidelines directly with the City. Mortgages Done Right does not administer the program.
Buying in Westlake at 62+? Ask About HECM for Purchase
HECM for Purchase is an FHA-insured reverse-mortgage option that allows eligible borrowers age 62 or older to purchase a home as their principal residence.
Age & Primary Residence
The borrower must be 62 or older, and the home must be the borrower’s principal residence.
Funds Needed at Closing
The buyer brings the funds required at closing. The amount depends on age, property value, interest rates and program calculations, so it varies by borrower and home.
Monthly Payment & Ongoing Responsibilities
There is no required monthly principal-and-interest payment while program requirements are met. The borrower must continue paying property taxes, homeowners insurance and HOA obligations, and maintain the property.
Counseling & New Construction
HUD-approved HECM counseling is required before the loan can move forward. New construction can be eligible, subject to FHA and HECM property requirements, so the home and its completion timeline should be reviewed early.
HECM for Purchase will not fit every buyer. Greg can compare it with traditional financing so you can weigh the upfront funds required, ongoing obligations and how the loan balance may change over time.
Financing Options Beyond the Standard Builder Mortgage
Some Westlake buyers are purchasing their first home. Others are relocating, selling an existing residence, moving from eastern Palm Beach County or purchasing a larger home for a growing family.
The financing plan may need to consider proceeds from another sale, current mortgage obligations, deposits, reserves, temporary housing, closing coordination and whether qualification is possible before the current home sells.
Greg also assists self-employed borrowers, business owners, retirees and buyers whose income or asset structure requires more flexible underwriting than the builder lender provides.
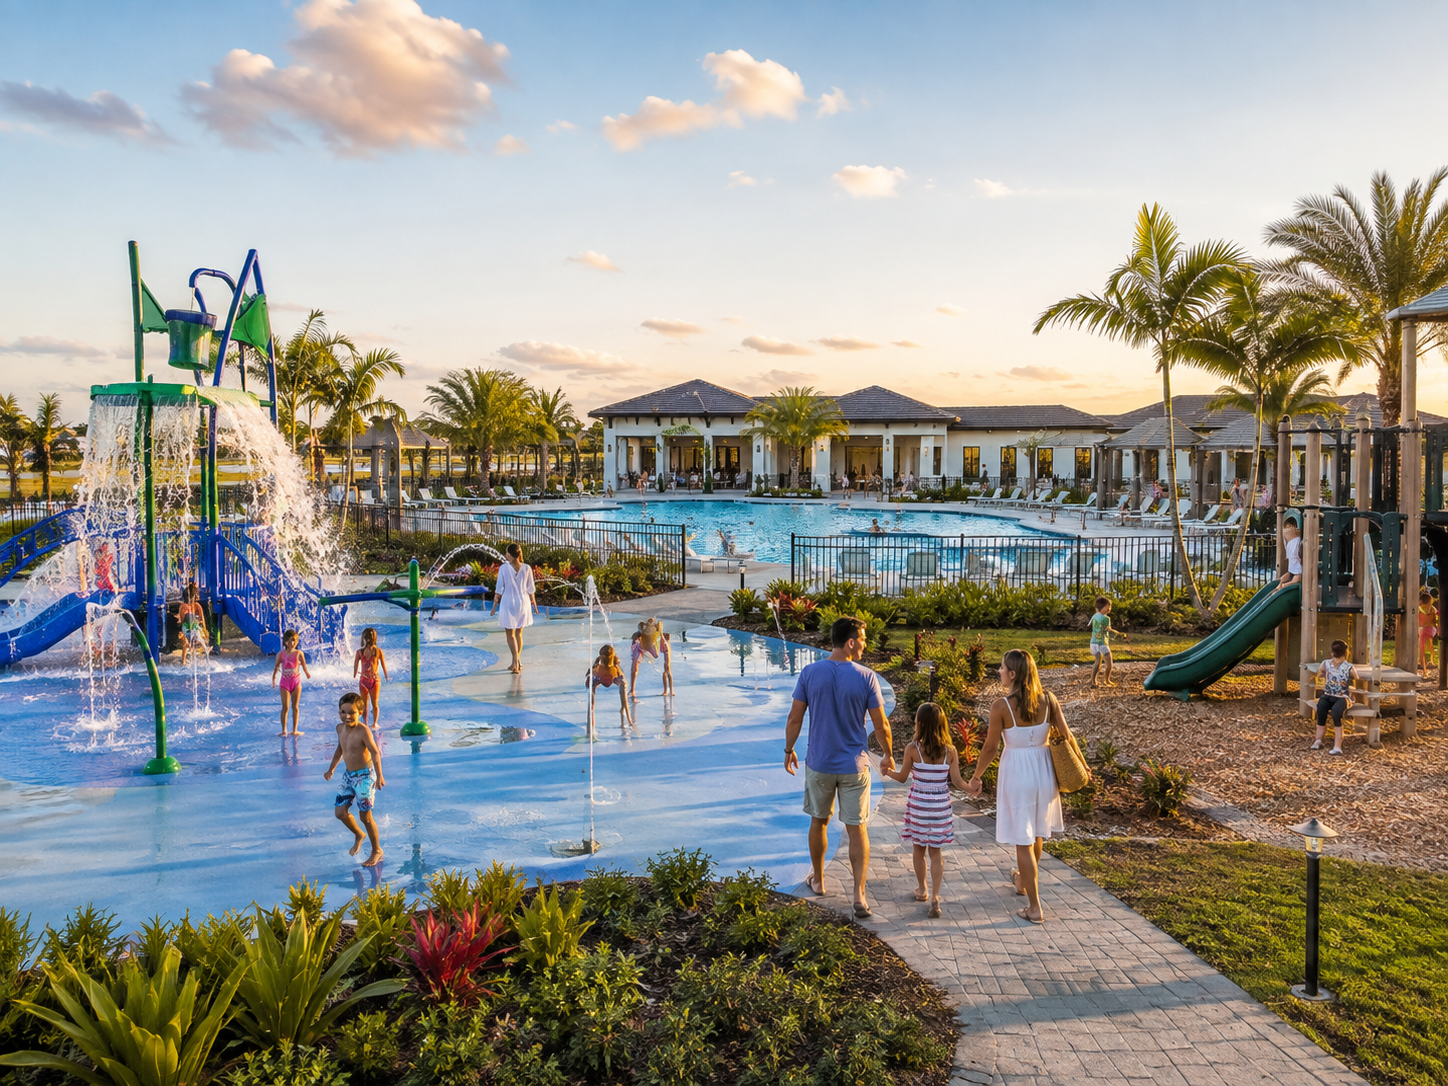
Modern Homes, Resort-Style Amenities and Continued Western Growth
Westlake combines new construction, planned neighborhoods, recreational amenities and expanding retail and services in western Palm Beach County.
New Homes and Townhomes
Modern single-family residences, townhomes and larger estate-style models for varied household needs.
Resort-Style Amenities
Pools, recreation areas, sports facilities, playgrounds, green space and community events.
Growing Retail and Services
Continued development is bringing shopping, dining, healthcare and additional conveniences farther west.
Family and Relocation Buyers
Buyers seeking newer homes, community amenities and additional space within Palm Beach County.
Retirees and 55+ Buyers
Financing may consider pensions, Social Security, retirement distributions, investment income and eligible assets.
Nearby Rural Communities
Convenient access to Loxahatchee, The Acreage, Wellington and western Palm Beach County.
Why Westlake Buyers Work With Greg Hayden
Receive a direct, honest comparison from an experienced Palm Beach County mortgage broker who can evaluate both builder financing and outside wholesale alternatives.
Direct Access to Greg
Work directly with Greg Hayden from the initial financing comparison through underwriting and closing.
Honest Builder Comparison
When the builder’s preferred financing is strongest, Greg will tell you rather than forcing an outside loan.
25+ Wholesale Lenders
Compare conventional, government, jumbo, Non-QM and specialty programs from a broad lender network.
Complex Borrower Experience
Guidance for self-employed buyers, veterans, retirees, investors and borrowers with nontraditional income.
Mortgage Help Across Western Palm Beach County
Mortgages Done Right serves buyers throughout Westlake, Loxahatchee, The Acreage, Wellington, Palm Beach Gardens, West Palm Beach and communities across Palm Beach County.
Frequently Asked Questions
Should I use the Westlake builder’s preferred lender?
The builder lender may offer valuable incentives and could provide the strongest overall package. Compare the rate, APR, points, fees, credits, mortgage insurance and long-term payment before deciding.
Can another lender match a builder incentive?
Sometimes, but not always. Builder incentives may be subsidized and tied to an affiliated or approved lender. An outside lender may instead provide better qualification or another program.
What is a mortgage-rate buydown?
A buydown uses upfront funds to reduce the interest rate temporarily or permanently. The cost and long-term benefit should be compared with other available incentives.
What happens if construction is delayed after I lock?
The lender may offer an extension, but additional costs or updated qualification may apply. Extended-lock and float-down terms should be reviewed before locking.
Can I use FHA or VA financing to purchase in Westlake?
Potentially, subject to borrower eligibility, property requirements, builder acceptance and the specific home or contract.
Can self-employed buyers use bank statements?
Eligible borrowers may qualify using personal or business bank statements, profit-and-loss documentation, assets or other approved Non-QM methods.
Can I qualify before selling my current home?
Possibly. Qualification depends on current mortgage obligations, income, assets, reserves, proposed occupancy and the new loan program.
Does Westlake offer home-purchase assistance?
The city operates the HAPPY program for eligible buyers, subject to current requirements, available funding and lender approval. Verify current terms directly with the City of Westlake.
Speak With a Westlake Mortgage Broker
Contact Greg Hayden to compare builder financing with conventional, FHA, VA, jumbo, bank-statement, asset-based and other mortgage options.